
12 Biotechs in Hong Kong's 18A Queue, and What Each Says It Will Spend the Money On
06 October 2026 | Tuesday | Analysis
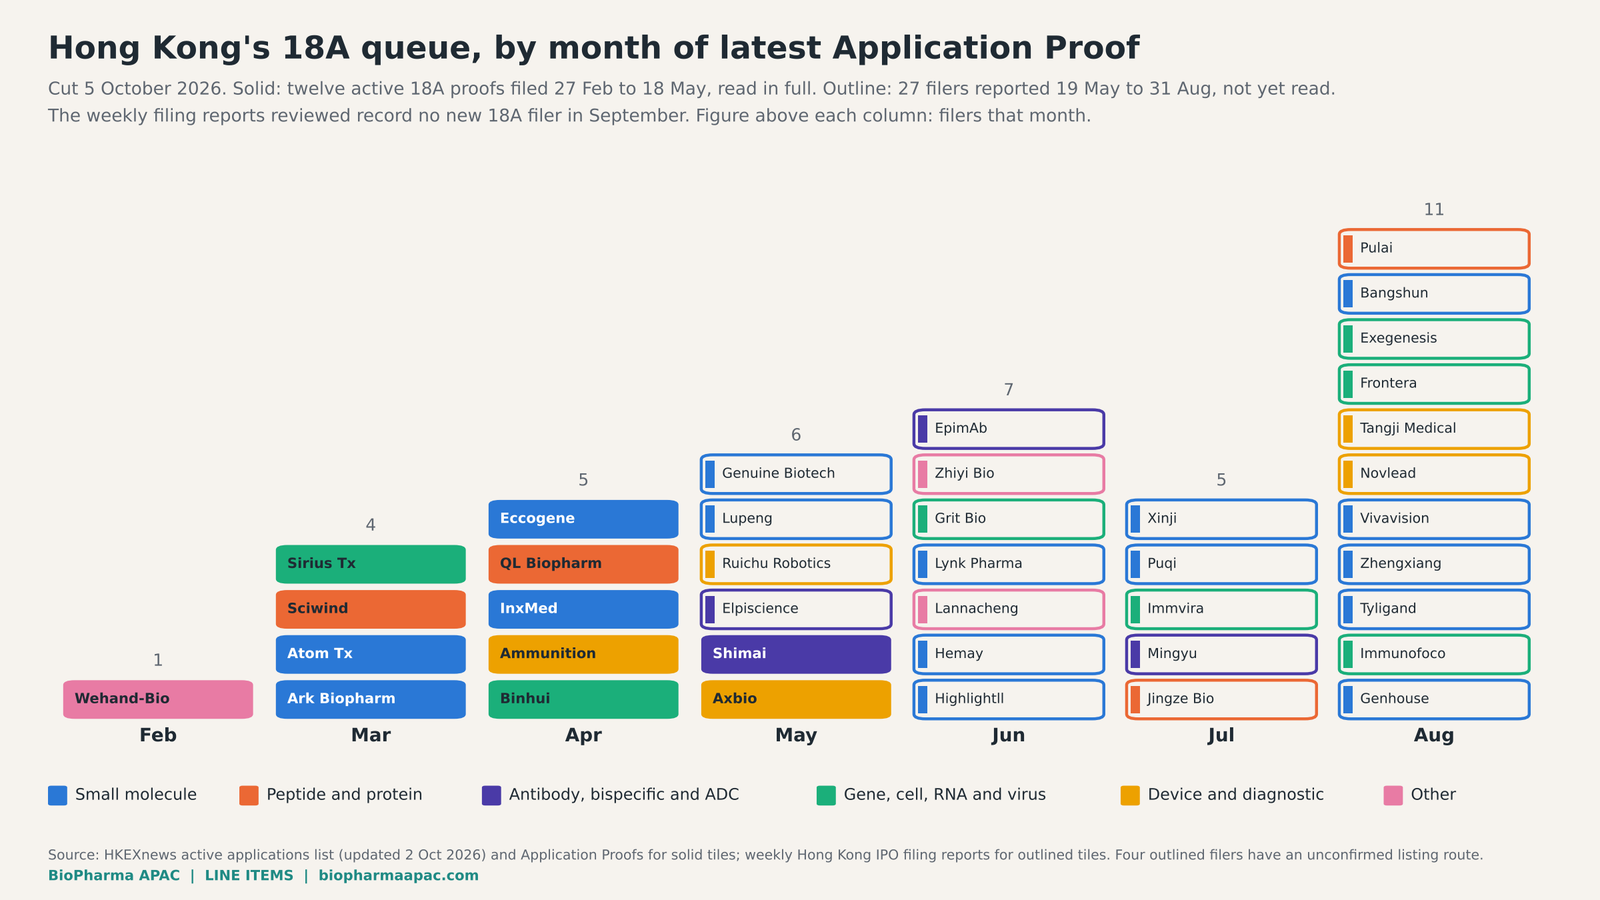
Figure 1. The 18A queue by month of latest Application Proof, coloured by the modality of each applicant's lead asset. Solid tiles are the twelve read in full; outlined tiles are later filers reported in the press.
Every Hong Kong biotech applicant has to tell investors what it will do with the money it raises. On the evidence of the twelve 18A application proofs that are active at our cut date, none of them will yet say how much goes where.
In all twelve, every percentage in the Future Plans and Use of Proceeds section is redacted, and so is every Hong Kong dollar figure and the size of the offering itself. The split reaches the public only after a company passes its listing hearing and posts its post-hearing information pack. What the proof does show is the shopping list itself: which trials, in which countries, in what order, and whether any money is set aside for a factory, a launch or a payment owed to somebody else. The order of those lines is the only signal of priority the market gets at this stage, and it says more than the redactions suggest.
The second thing the queue shows is that it rarely clears on the first attempt. Ten of the twelve have filed before. Axbio is on its third proof and Wuhan Ammunition refiled within days of its first proof lapsing. Until August, a proof lapsed six months after filing, forcing a six-monthly round of refreshed accounts and fees. That changed on 21 August 2026, when HKEX granted a temporary waiver extending the validity of eligible new listing applications from six to twelve months. The waiver covers applications that were still valid on that date or are filed afterwards, and it runs until 20 August 2029. The practical result is visible on the active list: Beijing Wehand-Bio, which filed on 27 February, is still shown as Active seven months later.
|
The queue in seven numbers |
The twelve, in order of Application Proof date
1 Beijing Wehand-Bio Pharmaceutical 北京五和博澳藥業
Filing and status. Application Proof 27 February 2026, first filing. Active.
Lead asset and stage. Three core products, all in China. WH007 is a natural medicine (Category 2.3) for polycystic ovary syndrome, with a Phase II IND approved in December 2025. WH006 is a natural medicine for obesity, in Phase II since August 2025. WH002 is a paclitaxel-cholesterol conjugated lipid emulsion for neoadjuvant Luminal breast cancer, with Phase III planned for 2026. The company already sells Sangbo'en (SZ-A) for type 2 diabetes, with revenue of RMB208.0 million in 2024 and RMB207.3 million in the first nine months of 2025.
Sponsors. Huatai Financial Holdings (Hong Kong), sole sponsor.
What the proceeds are for. Line items in filed order: the three core products through Phase III and launch preparation, which the proof dates to 2030 to 2032; capacity for a Sangbo'en tablet line in Beijing and an API line in Guangxi; working capital.
Pre-IPO rounds and cash. Seven rounds, about RMB1.1 billion in total. The latest, Series B+3 for RMB100 million on 30 September 2025, came from the Beijing Pharmaceutical Fund and Beijing Gongrong Shunxi. Cash was RMB162.3 million at 30 September 2025.
The signal. This is an 18A applicant with a commercial product, which shows how the chapter is now being used: the 18A label attaches to the core products, not to the company's revenue line. It is also the only applicant whose core products are natural medicines, and Beijing industry funds wrote both of its two most recent rounds.
2 Shanghai Ark Biopharmaceutical 上海愛科百發
Filing and status. Application Proof 17 March 2026, a refiling of a September 2025 application. Active.
Lead asset and stage. Ziresovir, an oral small-molecule RSV F protein inhibitor for infants aged one to 24 months. The NMPA accepted the NDA in August 2025, and the Business section says it has entered technical review, with approval expected in 2026. The second core product, AK3280, is a fibrosis inhibitor for idiopathic pulmonary fibrosis with a China Phase III planned for 2026. There are six candidates in all and no revenue.
Sponsors. CITIC Securities (Hong Kong) and J.P. Morgan Securities (Far East), joint sponsors.
What the proceeds are for. Ziresovir trials in Chinese adults and in US infants and adults; AK3280 Phase III in China and Phase II in the US; other candidates; milestone payments under in-licensing agreements; commercialisation in China; working capital.
Pre-IPO rounds and cash. Nine rounds totalling more than US$220 million. The latest, Series D for RMB190 million, closed in June 2022. Cash was RMB39.0 million and 2025 R&D expense RMB152.9 million.
The signal. Ark's last private round closed in June 2022; only Axbio's is older. A listing here stands in for a private market that stopped writing follow-on cheques. One line of the proceeds goes back out of the company: both core products were licensed in from Roche, so some IPO money will pay milestones to the licensor.
3 Atom Therapeutics 杭州新元素藥業
Filing and status. Application Proof 20 March 2026, a refiling of a September 2025 application. Active.
Lead asset and stage. ABP-671, an oral URAT1 inhibitor for first-line gout, in Phase 2b/3 in the US and China. The US Phase 2b is complete, and a pre-Phase 3 meeting request went to the FDA in January 2026.
Sponsors. CITIC Securities (Hong Kong), sole sponsor.
What the proceeds are for. ABP-671 leads with five studies: Phase 3 in gout in the US and Australia, Phase 2 in chronic kidney disease, Phase 3 in refractory and in tophaceous gout, and the China Phase 2b/3. Then ABP-745 in flares, atherosclerosis and rare diseases; then platforms, including AI; then working capital.
Pre-IPO rounds and cash. Six rounds, RMB1.18 billion in total. Series D (RMB552.2 million, August 2025) and Series D+ (RMB100 million, November 2025) came in the six months before filing. Cash was RMB184.9 million, plus RMB140.0 million in financial assets and RMB21.3 million in term deposits. 2025 R&D expense was RMB179.7 million.
The signal. This is the most US-first plan in the queue: the first line item is a Phase 3 in the US and Australia, not China. China rights for gout are already with CMS, which had paid RMB80 million by the latest practicable date. The IPO is meant to fund the global half of the asset.
4 Hangzhou Sciwind Biosciences 杭州先為達
Filing and status. Application Proof 23 March 2026, a refiling of a September 2025 application. Active.
Lead asset and stage. Ecnoglutide (XW003), a once-weekly injectable GLP-1 receptor agonist that the company describes as cAMP-biased. The NMPA approved it for type 2 diabetes in January 2026 and for overweight and obesity in March 2026. Revenue was RMB133.5 million in 2025. The pipeline has eight programmes, including oral ecnoglutide and an oral small molecule.
Sponsors. Morgan Stanley Asia and China International Capital Corporation Hong Kong Securities, joint sponsors.
What the proceeds are for. Ecnoglutide trials in China in adolescent obesity, MASH and obstructive sleep apnoea, plus registration; the two oral programmes; four earlier candidates; manufacturing and quality control; working capital.
Pre-IPO rounds and cash. About RMB2.2 billion across rounds since 2018. The latest, Series D (RMB680 million including transfers, December 2024), came from Hanhai Information, Guangxi Tencent and SSF YRD Investment. Cash was RMB839.1 million, second only to Sirius in the twelve. 2025 R&D expense was RMB158.8 million.
The signal. Sciwind is an approved GLP-1 maker asking 18A investors to fund label expansion and a factory. It has partners for China commercialisation (Pfizer, December 2025), Korea (inno.N) and the oral programmes outside Greater China (Verdiva), so the proceeds plan is about indications and supply rather than reach.
5 Sirius Therapeutics 靖因藥業
Filing and status. Application Proof 31 March 2026, a refiling of a September 2025 application. Active.
Lead asset and stage. SRSD107, an siRNA targeting Factor XI, for thromboembolic disease. It is in Phase 2 for prevention of venous thromboembolism in Europe and China, with a primary readout expected in the second half of 2026. Phase 3 studies are planned in cancer-associated thrombosis from the second half of 2027 and in atrial fibrillation patients unsuited to DOACs in 2028, subject to Phase 2 results.
Sponsors. Goldman Sachs (Asia), Haitong International Capital and HSBC Corporate Finance (Hong Kong), joint sponsors.
What the proceeds are for. Global Phase 3 trials of SRSD107 in both planned indications, plus CMC and toxicology; global trials of SRSD216 (Lp(a), in Phase 2 in China and the US); SRSD384 for obesity; the wider pipeline, including extrahepatic programmes; working capital and business development.
Pre-IPO rounds and cash. About US$144.0 million over Series A, B and B2, led from Series A by OrbiMed. The latest, US$47.5 million, closed in April 2025. Cash was RMB1,172.6 million, of which RMB1,084.5 million was in time deposits. 2025 R&D expense was RMB213.3 million.
The signal. Sirius's plan is built around a global Phase 3 it will fund half of. In May 2025 it signed with CRISPR Therapeutics to co-develop SRSD107 on 50:50 global economics, for US$25 million in cash and US$70 million in CRISPR stock upfront, with more than US$800 million in total. Its cash pile is partly partner money: contract liabilities stood at RMB667.7 million at year-end.
6 Binhui Biopharmaceutical 武漢濱會
Filing and status. Application Proof 2 April 2026, a refiling of a September 2025 application. Active.
Lead asset and stage. BS001 (OH2), an HSV-2 oncolytic virus that secretes GM-CSF, for third-line or later unresectable or metastatic melanoma. Completion of the China Phase III is targeted for the fourth quarter of 2026, and US Phase III trials are expected to start the same quarter.
Sponsors. Huatai Financial Holdings (Hong Kong), CMB International Capital and BOCI Asia, joint sponsors.
What the proceeds are for. BS001 trials in melanoma, glioblastoma, colorectal cancer, soft tissue sarcoma, biliary tract cancer and other solid tumours, plus registration and commercialisation; two follow-on assets, BS006 and BR003; preclinical work; working capital.
Pre-IPO rounds and cash. Seven rounds, about RMB1.04 billion. Lepu Biopharma led Series A in 2018 and Yangtze River Pharmaceutical the Series B+. The latest, a RMB20 million follow-on, closed in December 2023. Cash was RMB125.6 million, plus RMB178.0 million in time deposits and RMB76.3 million in financial assets. 2025 R&D expense was RMB84.3 million.
The signal. Binhui is the furthest along on the mainland side of the process: press reports in early September said its CSRC overseas listing filing notice had been issued, covering up to 38.1 million H shares. Its proceeds list is the longest indication list in the twelve for a single asset, which is how a platform modality looks when it has one product.
7 Wuhan Ammunition Life-tech 武漢艾米森
Filing and status. Application Proof 7 April 2026, a second filing made after the first lapsed. Active.
Lead asset and stage. Two NMPA Class III approved DNA methylation tests: IHepcomf, a blood test for early detection of liver cancer (approved January 2025, CE-IVD 2022), and IUrisure, a urine test for urothelial cancer (approved October 2025). Revenue was RMB15.4 million in 2025.
Sponsors. CCB International Capital and BOCOM International (Asia), joint sponsors.
What the proceeds are for. The core tests, including an MRD indication, a pivotal trial in Europe and commercialisation; pipeline tests for gastric, lung, endometrial and pan-cancer detection; the detection platform, equipment, reagents and production automation; acquisitions or in-licensing; working capital.
Pre-IPO rounds and cash. About RMB240 million over six rounds since 2016, on our sum of the History section, the latest RMB20 million in January 2026. Cash was RMB54.7 million and 2025 R&D expense RMB21.3 million, the lowest in the twelve.
The signal. This is a diagnostics company using the biotech chapter, with approved products and a small capital history. It is also one of only two applicants to earmark money explicitly for acquisitions or in-licensing, and the only one whose ex-China plan points to Europe rather than the US.
8 InxMed
Filing and status. Application Proof 21 April 2026, a refiling of an August 2025 application. Active.
Lead asset and stage. Ifebemtinib (IN10018), an oral FAK inhibitor acquired from Boehringer Ingelheim in 2017, in a registrational Phase III in China for platinum-resistant ovarian cancer with pegylated liposomal doxorubicin. An NDA is expected in the second half of 2026.
Sponsors. CITIC Securities (Hong Kong) and CCB International Capital, joint sponsors.
What the proceeds are for. Ifebemtinib in ovarian cancer (trials, approval preparation and CMC), then lung and colorectal cancer, then combinations with ADCs, then a China launch; other pipeline assets, including three ADCs; preclinical research; manufacturing capacity; working capital.
Pre-IPO rounds and cash. About RMB929.3 million. The latest, a Series C of US$33.72 million, closed in January 2025. Cash was RMB210.3 million and 2025 R&D expense RMB100.9 million.
The signal. InxMed is the closest of the small-molecule applicants to a China NDA, and its proceeds plan runs all the way to launch. For InxMed, the IPO is a bridge from a registrational readout to commercial revenue rather than a research fund. The Chinese name used in the press, 應世生物, does not appear in the proof pages we read.
9 Beijing QL Biopharmaceutical 北京質肽
Filing and status. Application Proof 24 April 2026, first filing. Active.
Lead asset and stage. Zovaglutide (ZT002), a once-monthly GLP-1 receptor agonist peptide injection, in the HORIZON-1 Phase III for obesity in China. The company says it is discussing a US Phase II bridging or Phase III study with the FDA.
Sponsors. Jefferies Hong Kong and Huatai Financial Holdings (Hong Kong), joint sponsors.
What the proceeds are for. Zovaglutide Phase III and switch studies in China, a planned US Phase II/III, trials in diabetes and MASH, and pre-commercialisation; the oral peptide ZT006, the dual agonist ZT003 and four preclinical programmes; a second manufacturing facility; working capital.
Pre-IPO rounds and cash. About RMB1.11 billion, per the Summary. A Series C of RMB680.6 million, with OrbiMed and Qiming among the investors, was agreed on 19 January 2026. Year-end cash of RMB31.2 million therefore predates the round. 2025 R&D expense was RMB176.1 million.
The signal. QL is the queue's second GLP-1, betting that monthly dosing differentiates it in a class where China already has approved local entrants, Sciwind's among them. Its January round was the largest private raise among the twelve in 2026, agreed three months before filing, which is the classic sequence of a crossover round ahead of a listing.
10 Eccogene 誠益生物
Filing and status. Application Proof 29 April 2026, a refiling of an October 2025 application. Active.
Lead asset and stage. ECC4703, an oral, liver-targeting THR-beta full agonist for MASH and obesity, with the first patient enrolled in a US Phase II in December 2025. Its key product, ECC5004, is an oral small-molecule GLP-1 agonist licensed to AstraZeneca in November 2023 for US$185 million upfront and up to US$1.825 billion in milestones, now in Phase IIb.
Sponsors. Jefferies Hong Kong, Merrill Lynch (Asia Pacific) and China International Capital Corporation Hong Kong Securities, joint sponsors.
What the proceeds are for. ECC4703 global Phase IIa studies, one of them as an add-on to semaglutide in obesity and one in MASH, plus CMC; Eccogene's share of ECC5004 Phase III costs; ECC0509 in osteoarthritis pain; preclinical programmes and its platform; working capital.
Pre-IPO rounds and cash. About US$82.7 million. AstraZeneca itself wrote the latest round, a US$25.0 million Series C in December 2023. Cash was US$55.9 million and 2025 R&D expense US$36.7 million.
The signal. Eccogene is the clearest case in the queue of IPO money flowing into a partner's programme: one line pays its share of a Phase III that AstraZeneca is running. It is also positioning its lead asset as an add-on to semaglutide rather than a rival to it.
11 Axbio International 安序源
Filing and status. Application Proof 14 May 2026, its third filing after April and November 2025. Active.
Lead asset and stage. AxiLona EL-100, an electrochemistry-based microarray molecular diagnostic analyser with a Jiangsu Class II registration (April 2025) and CE marking (July 2023). Next is AXP-100, which the company calls an electrochemical sequencing platform, with a clinical trial planned for the third quarter of 2026.
Sponsors. China International Capital Corporation Hong Kong Securities and SPDB International Capital, joint sponsors.
What the proceeds are for. EL-100: protein detection, China and US registrational trials, a sales team, academic marketing and a production line upgrade. AXP-100: optimisation, trials, commercialisation and a new production line. Then AXP-1000 and the pipeline, the core technology platform and working capital.
Pre-IPO rounds and cash. About US$115.7 million. The latest, a US$70 million Series B, closed in May 2022. Cash was US$24.6 million and 2025 R&D expense US$8.9 million.
The signal. Axbio has filed three times in thirteen months, and its last private round, in May 2022, is the oldest in the twelve. It is an instrument maker using the biotech chapter, and two of its five proceeds lines include a production line.
12 Zhejiang Shimai Pharmaceutical 浙江時邁藥業
Filing and status. Application Proof 18 May 2026, a second filing after November 2025. Active.
Lead asset and stage. Two core products. DNV3 is a fully human anti-LAG-3 monoclonal antibody in Phase II in China for melanoma, in combination with anti-PD-1 and chemotherapy. SMET12 is an EGFR x CD3 bispecific T-cell engager in Phase IIa in China, led by oesophageal cancer, with a US IND cleared in 2021.
Sponsors. Huatai Financial Holdings (Hong Kong), sole sponsor.
What the proceeds are for. DNV3 trials and filing in China, then global trials and registration in the US, Europe and Australia; SMET12 Phase II expansion, a Phase III start, and CMC and NDA preparation; two further T-cell engagers; mergers, acquisitions and investments in T-cell engager and antibody technology; working capital.
Pre-IPO rounds and cash. Four rounds, about RMB690.1 million, of which about 73.82% had been used. The latest, a RMB170.1 million pre-IPO round, was agreed in January 2026. Cash was RMB33.9 million and 2025 R&D expense RMB46.6 million.
The signal. Shimai is the only antibody company in the twelve and the only one to earmark money for M&A in its own modality. Its global trial plan is the broadest by geography in the queue, on a 2025 R&D budget that was among the smallest.
What the queue wants money for
Read side by side, the twelve lists are more alike than the science behind them.
Every list puts its core product first and working capital last. In between, four kinds of spending recur. The first is trials outside mainland China. Eight of the twelve name US, European, Australian or global studies. For Atom Therapeutics, Sirius and Eccogene these lead their lists rather than trailing them. Hong Kong investors are being asked to fund the global development that licensing partners used to buy.
The second is factories. Five applicants list a production line, a second facility or manufacturing capacity in its own right: Wehand-Bio, Sciwind, InxMed, QL and Axbio. Each has an approved product or a Phase III programme: this is the line item of companies expecting to sell soon.
The third is money that leaves the company. Ark will pay in-licensing milestones to Roche, and Eccogene will pay its share of an AstraZeneca-run Phase III. Sirius sets aside business development funds, and Wuhan Ammunition and Shimai set aside money to acquire or license assets. In five of the twelve, part of the IPO is not for the company's own laboratories.
The fourth is launch. Seven plans include commercialisation, launch preparation or a sales team. That is the largest change from the 18A queue of the chapter's early years, when the typical applicant was a Phase I or Phase II company selling a research story. Four of these twelve already have a product approved or on sale, and among the 27 filers behind them press reports describe at least ten with an approved or marketed product.
One theme is concentrated rather than spread. Four of the twelve have a core programme in obesity or metabolic disease: Wehand-Bio's WH006, Sciwind's ecnoglutide, QL's zovaglutide and Eccogene's ECC4703. Two are GLP-1 agonists headed for the same Chinese market.
Behind them: 27 filers reported since 19 May
These companies were reported in weekly Hong Kong IPO filing round-ups as having filed or refiled under Chapter 18A between 19 May and 31 August 2026. We have not yet read their proofs. Details are as reported, sponsors where reports agree, and every entry will be checked against HKEXnews before it moves into the main list. Four marked with an asterisk had no listing route stated in the reports we found. By those reports, at least 22 of the 27 are refilings, twelve lead with a small molecule, and China International Capital Corporation is a sponsor on at least nine.
|
Company |
Filed (filing no.) |
Lead asset as reported |
Sponsors as reported |
|
Elpiscience 科望醫藥 |
27 May (4th) |
ES102 OX40 agonist antibody, clinical |
China Securities International |
|
Ruichu Robotics 睿觸機器人 |
27 May (2nd (reported)) |
RC120 percutaneous puncture robot, approved |
Everbright |
|
Lupeng Pharmaceutical 麓鵬製藥 |
28 May (2nd) |
LP-168 fourth-generation BTK inhibitor, NMPA conditional approval Jun 2026 |
China Securities International |
|
Genuine Biotech 真實生物 |
29 May (4th) |
Azvudine oral antiviral, marketed |
not reported |
|
Highlightll Pharmaceutical 高光製藥 |
8 Jun (2nd) |
TLL-018 TYK2/JAK1 inhibitor, Phase III |
CICC (others reported variously) |
|
Hemay Pharmaceutical 和美藥業 |
8 Jun (3rd) |
Mufemilast PDE4 inhibitor (psoriasis), approved Sep 2025 |
reported variously |
|
Lannacheng Bio 藍納成 |
11 Jun (2nd) |
18F-LNC1001 PSMA PET radiodiagnostic, NDA stage |
CICC |
|
Lynk Pharmaceuticals 凌科藥業 |
15 Jun (1st) |
LNK01001 oral JAK1 inhibitor, Phase III |
reported variously |
|
Grit Biotechnology 君賽生物 |
16 Jun (2nd) |
GC101 TIL cell therapy (melanoma), registrational Phase II |
CITIC |
|
Zhiyi Biotech* 知易生物 |
18 Jun (1st) |
SK08 live biotherapeutic, late-stage clinical |
CICC; Industrial Securities International |
|
EpimAb Biotherapeutics 岸邁生物 |
24 Jun (3rd) |
Bispecific antibodies and T-cell engagers, four clinical assets |
CITIC; Bohai |
|
Jingze Biotech 景澤生物 |
3 Jul (1st) |
JZB30 recombinant FSH, approved Apr 2025; JZB05 anti-VEGF, Phase III |
CICC; Guoyuan International |
|
Mingyu Pharmaceutical 明宇製藥 |
8 Jul (2nd) |
MHB036C TROP-2 ADC; MHB018A IGF-1R antibody, Phase III |
Morgan Stanley; BofA; CITIC |
|
Immvira 亦諾微醫藥 |
16 Jul (3rd) |
MVR-T3011 HSV-1 oncolytic virus, Phase II |
Citi; CICC |
|
Puqi Pharmaceutical 普祺醫藥 |
24 Jul (2nd) |
PG-011 JAK1/2 topical gel and nasal spray, NDA accepted Feb 2026 |
CICC (reported variously) |
|
Xinji Pharmaceutical 新濟醫藥 |
24 Jul (2nd) |
Dexmedetomidine microneedle patch, Phase II |
Guotai Haitong |
|
Genhouse Bio* 勤浩醫藥 |
7 Aug (2nd) |
GH31 synthetic lethal (licensed to Gilead); RAS pipeline |
Huatai International |
|
Immunofoco* 易慕峰 |
18 Aug (refiling (reported)) |
IMC002 CLDN18.2 CAR-T, Phase III |
Huatai International |
|
Tyligand Bioscience* 泰勵生物 |
21 Aug (2nd) |
TSN1611 oral KRAS G12D inhibitor, Phase II |
CICC |
|
Zhengxiang Pharmaceutical 征祥醫藥 |
26 Aug (2nd) |
PA inhibitor (influenza), approved 2025 |
CICC |
|
Vivavision Biotech 維眸生物 |
28 Aug (2nd) |
VVN461 JAK1/TYK2 (uveitis), Phase III |
CICC |
|
Novlead 諾令生物 |
28 Aug (2nd) |
iNOwill inhaled nitric oxide device, commercial |
CCB International |
|
Tangji Medical 糖吉醫療 |
28 Aug (2nd) |
Gastric bypass stent system, approved Jan 2024 |
reported variously |
|
Frontera Therapeutics 芳拓生物 |
28 Aug (2nd) |
rAAV gene therapy (eye, cardiovascular), clinical |
UBS; Guotai Haitong |
|
Exegenesis Bio 嘉因生物 |
28 Aug (2nd) |
EXG102-031 AAV (wet AMD), Phase IIa |
CCB International |
|
Bangshun Pharmaceutical 邦順製藥 |
30 Aug (2nd) |
JAK2 inhibitor (myelofibrosis), approved Apr 2026 |
China Securities International |
|
Pulai Pharmaceutical 普萊醫藥 |
31 Aug (2nd) |
PL-5 antimicrobial peptide spray, approved Jun 2026 |
CITIC |
* Listing route not stated in the reports found. Filing dates are as reported; where reports differ we show the earliest. English names are those used in company or press materials, or a transliteration.
|
Outside the count Chapter 18C. The weekly round-ups we reviewed record no biotech or medtech applicant under Chapter 18C, the specialist technology route, in 2026. A+H filers. Healthcare companies already listed in Shanghai or Shenzhen are filing in Hong Kong under the ordinary Main Board rules. Fourteen were reported between 18 May and 30 September, including Sinocelltech (神州細胞), Sichuan Biokin (百利天恒), Zelgen (澤璟製藥), Dizal (迪哲醫藥), Betta (貝達藥業), InventisBio (益方生物) and Salubris (信立泰). Listed, so excluded. Six 18A applicants listed between 22 May and 30 June and are no longer in the queue: Danuo (丹諾醫藥), Tianchen (天辰生物), Huajian Weilai (華健未來), Maike (麥科醫藥), Libang (禮邦醫藥) and True Health (真健康醫療). |
What December will show
The redactions will not last. Each applicant that passes its hearing posts a post-hearing information pack with the split filled in, and that is the point at which this ledger can show where the money is weighted, not just what it is for. Until then, the order of the lines, the countries named and the presence or absence of a factory, a launch or a partner payment are the most reliable early reading of what each company expects to happen next.
The twelve-month validity window changes how that reading should be used. A proof filed in February can now stay active into 2027 without being refreshed. The longer a company sits on the list, the more the gap matters between the plan it filed and the trial readouts, partnering news and private rounds that follow. Weekly updates will record those changes against each entry
Disclaimer
Not investment advice. This article describes public filings. It is not a recommendation to buy, sell or subscribe for any security, and it takes no view on valuation, offer pricing or likelihood of listing.
Method in brief
Who is in the list. Main Board applicants carrying the "B" marker for Chapter 18A, the pre-revenue biotech route. Each one is shown as Active on the HKEXnews active applications list (updated 2 October 2026), with an Application Proof filed between 27 February and 18 May 2026. That gives twelve companies, and each proof was read in full.
Who is behind them. Twenty-seven 18A filers were reported in weekly Hong Kong IPO filing round-ups between 19 May and 31 August. They appear in a second table with the details reported in the press. Each will be read from its own proof and moved into the main list in weekly updates.
What we read. In each proof: the Summary, the parties involved in the offering, history and pre-IPO investments, financial information, and the Future Plans and Use of Proceeds section. Figures are shown as filed, in the currency filed, at 31 December 2025 unless stated. Entries run in order of Application Proof date.
What we leave out. Valuations, estimates of offer size and investment views. Proofs record post-money valuations for private rounds; we report the round and leave the valuation out.
Updates. This ledger updates in place, with a dated note each week, until our year-end review of 2026 listings publishes in December.
Most Read
- Can APAC Biomanufacturing Decarbonise Without Pricing Itself Out?
- The Algorithm on the GMP Floor: AI Promises a Smarter Plant. Regulators Demand the Audit Trail.
- APAC's Peptide-Capacity Gamble
- After the Rush: APAC's mRNA and Vaccine Capacity Hangover
- The Biosimilar Race: Factory to the World — or Stuck in the Copycat Economy?
- The Vein-to-Vein Problem: Can APAC's Cold Chain Carry Advanced Therapies?
- Vectors, Plasmids and the CGT Trap: APAC's Cell and Gene Therapy Ambitions Face an Upstream Bottleneck
- Can APAC Build Radioligand Therapy Before the Atoms Decay?
- The Great Biopharma Reset: 50 Developments That Changed Everything in H1 2026
- Beyond the Trial: Can Real-World Evidence Earn Regulatory Trust in APAC?
- Beyond the Obvious Giant: Where APAC's Clinical Trials Go Next
- The Frontier That Won’t Quite Arrive
Bio Jobs
- Sanofi Turns The Page As Belén Garijo Steps In And Paul Hudson Steps Out
- Global Survey Reveals Nearly 40% of Employees Facing Fertility Challenges Consider Leaving Their Jobs
- BioMed X and AbbVie Begin Global Search for Bold Neuroscience Talent To Decode the Biology of Anhedonia
- Thermo Fisher Expands Bengaluru R&D Centre to Advance Antibody Innovation and Strengthen India’s Life Sciences Ecosystem
- Accord Plasma (Intas Group) Acquires Prothya Biosolutions to Expand Global Plasma Capabilities
- ACG Announces $200 Million Investment to Establish First U.S. Capsule Manufacturing Facility in Atlanta
- AstraZeneca Invests $4.5 Billion to Build Advanced Manufacturing Facility in Virginia, Expanding U.S. Medicine Production
News


